What is the scope and industry significance of the Drone Light Shows Market?
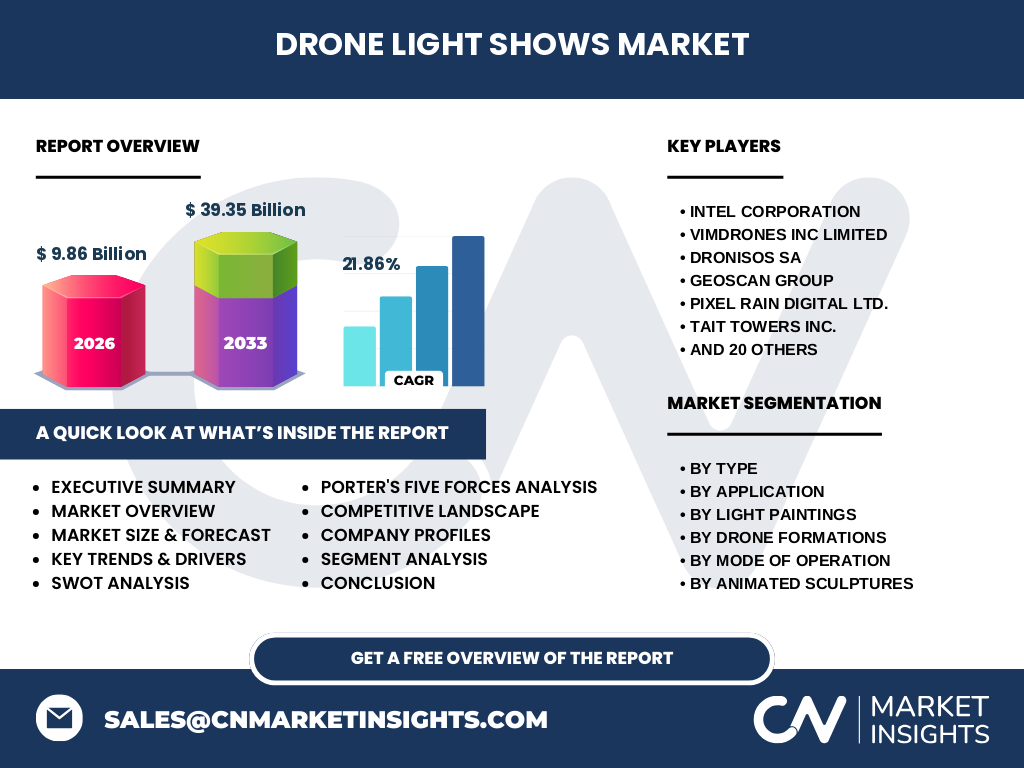
Our analysis indicates that the Drone Light Shows Market represents a transformative convergence of aerospace engineering, entertainment technology, and digital artistry, reaching a market size of 9.86 Billion in 2026. This burgeoning sector replaces traditional pyrotechnics with synchronized swarms of Unmanned Aerial Vehicles (UAVs) equipped with high-luminance LEDs, serving as a critical high-margin revenue stream for large-scale entertainment, municipal celebrations, and corporate branding initiatives globally.
What are the core drivers, restraints, challenges, and opportunities shaping the Drone Light Shows Market?
Structural growth is heavily propelled by stringent environmental regulations limiting hazardous pyrotechnic smoke and noise pollution, alongside advancements in Real-Time Kinematic (RTK) GPS positioning. Conversely, regulatory bottlenecks imposed by aviation authorities like the FAA and EASA regarding Night Operations and Beyond Visual Line of Sight (BVLOS) waivers create operational friction. However, massive untapped commercial opportunities in localized tourism marketing and immersive stadium events continue to offset these logistical hurdles.
Emerging trends and growth patterns in the Drone Light Shows Market
The market is experiencing a definitive shift toward ultra-dense swarm choreography and hyper-realistic multi-color spectrum transitions. Innovators are increasingly integrating AI-driven autonomous collision avoidance algorithms directly into the onboard flight controller firmware, bypassing traditional ground-station RF interference vulnerabilities. This technological evolution heavily favors tech-forward providers capable of scaling from localized 2D displays to complex, city-wide 3D spatial volumetric installations.
How did the COVID-19 pandemic affect the Drone Light Shows Market and dictate its recovery trajectory?
The pandemic initially caused severe supply chain fractures for critical rare-earth carbon-fiber airframes and high-brightness LED components sourced primarily from East Asian manufacturing hubs. Concurrently, strict social distancing mandates decimated the live events sector throughout 2020. However, the subsequent recovery trajectory has been exceptionally robust, as municipalities and event planners embraced touchless, open-air drone spectacles as a safe, socially distant alternative to traditional crowded indoor and stadium gatherings.
Competitive benchmarking and strategic dynamics in the Drone Light Shows Market
The competitive landscape is characterized by a mix of specialized aerial display pioneers and diversified robotics conglomerates. Market concentration is moderately fragmented at the regional level, though global leaders leverage proprietary ground-control software licenses and vast proprietary fleets to secure enterprise-level contracts. Strategic maneuvers heavily involve cross-border acquisitions of boutique animation studios and strategic distribution partnerships with major international entertainment conglomerates.
Executive summary of key findings in the Drone Light Shows Market
Our comprehensive research underscores an explosive expansion trajectory, projecting the market to surge from 9.86 Billion in 2026 to 39.35 Billion by 2033, registering a remarkable compound annual growth rate (CAGR) of 21.86%. Strategic success in this high-barrier-to-entry industry hinges on navigating complex multi-jurisdiction airspace regulations while simultaneously investing in proprietary fleet management software and high-lumen, weather-resistant UAV hardware architectures.
Market forecast and revenue trajectory from 2027 to 2033
The quantitative data suggests an accelerated adoption curve, driving the market from its 2026 baseline of 9.86 Billion toward the ambitious milestone of 39.35 Billion by the end of 2033. Achieving this 21.86% CAGR will require continuous software optimization to reduce crew sizes per show, thereby expanding gross operating margins and democratizing access for mid-tier regional event production companies.
Segmentation analysis across operational types, applications, and display configurations
The market demonstrates profound granularity when segmented by operational parameters and visual delivery mechanisms. Key analytical categories encompass:
- By Type: Drone Formations (2D, 3D, and Geometric Patterns), Animated Sculptures (Static and Dynamic), and Light Paintings (LED Light Trails and Color Variations and Effects).
- By Application: Exhibition, Cultural Performance, Tourist Attraction, and Other Applications.
- By Mode Of Operation: Remotely Operated, Semi-Autonomous, and Fully Autonomous.
Geographic distribution and regional performance across global territories
Geographic performance reveals stark disparities driven by local regulatory frameworks, venture capital availability, and municipal event spending power. North America and Europe currently command significant revenue shares due to early commercialization and advanced technical infrastructure, while Asia-Pacific is rapidly emerging as the fastest-growing regional market, catalyzed by massive government-backed smart city tourism initiatives and robust domestic drone manufacturing ecosystems.
In-depth regional review of high-potential territories
North American growth is heavily tethered to stringent FAA Part 107 waiver approvals and rigorous safety validation standards championed by domestic providers. Meanwhile, the Asia-Pacific territory benefits from streamlined regional municipal permitting processes and proximity to primary hardware manufacturing hubs in Shenzhen, enabling rapid fleet deployment and lower capital expenditure barriers for local operators entering the tourism attraction and cultural performance segments.
Company profiles and strategic positioning of leading market participants
The market features a dynamic ecosystem of specialized innovators and established aerospace entities. Industry pioneers such as Intel Corporation, Dronisos SA, Verge Aero Inc., and Firefly Drone Shows LLC continuously push the boundaries of swarm density and software reliability. Concurrently, specialized regional players like Skymagic Global Ltd., CollMot Entertainment Kft., and HighGreat Technology Co. Ltd. leverage localized market penetration and proprietary animation pipelines to capture lucrative municipal tourism and corporate exhibition contracts.
Porter's Five Forces analysis of the Drone Light Shows Market
An evaluation of competitive forces indicates moderate-to-high threat of new entrants restricted primarily by heavy R&D overhead in collision-avoidance software. Bargaining power of suppliers is moderate, concentrated around high-efficiency lithium-polymer battery cells and specialized RGB LED arrays. Buyer power remains constrained due to the highly specialized artistic and technical execution required, whereas the threat of substitution from traditional fireworks is steadily declining due to environmental and safety mandates.
SWOT analysis highlighting strategic strengths, weaknesses, opportunities, and threats
Core strengths include high visual impact and eco-friendly operations, contrasted with weaknesses such as high initial capital expenditure and sensitivity to adverse weather conditions like high winds and heavy precipitation. Significant opportunities lie in expanding autonomous fleet deployment for permanent tourist attractions, while primary threats encompass tightening global regulatory airspace restrictions and potential radio-frequency jamming in urban environments.
Value chain analysis from raw materials to end-user experiential delivery
The industry value chain begins with raw material sourcing for lightweight carbon-fiber composites, rare-earth magnets, and semiconductor microchips. This flows into tier-one component manufacturing, specialized software development for swarm trajectory mapping, and final assembly by drone hardware manufacturers. The chain culminates with specialized production studios and event operators executing the final shows for end-users spanning municipal authorities, corporate brands, and exhibition organizers.
Investment insights and strategic high-potential areas for capital deployment
Venture capital and private equity investors should prioritize companies developing proprietary, AI-driven autonomous ground-control software rather than hardware assembly alone, as software scalability yields vastly superior EBITDA margins. Furthermore, investments targeted at weather-resistant airframe engineering will unlock untapped markets in regions with historically volatile oceanic or northern climates, directly mitigating the weather-dependent operational restraints currently plaguing the industry.
Conclusion and strategic industry takeaways
The trajectory toward 39.35 Billion by 2033 cements this market as a cornerstone of modern experiential entertainment. Stakeholders must proactively adapt to evolving aviation regulations, invest in autonomous software redundancy, and forge strategic partnerships across municipal and corporate sectors to capture outsized market share during this high-growth expansion phase.
Research methodology for baseline estimation and data triangulation
Our baseline estimates and market sizing metrics are meticulously triangulated using a multi-tiered research methodology. This approach combines exhaustive bottom-up analysis of corporate trade registries, primary stakeholder interviews with chief technology officers and regulatory compliance officers, and top-down macro-economic modeling correlating live-event spending indices with municipal tourism budgets.
Scope of the report, coverage parameters, and operational limitations
This research report encompasses a global evaluation of the industry, covering commercial drone formation displays, animated sculptures, and light painting applications across all major operating modes. Limitations of this study include the exclusion of military swarm defense applications and recreational consumer drone usage, focusing exclusively on commercial, entertainment, and municipal exhibition deployment models.
Recent developments, strategic partnerships, and product launches
Recent industry momentum is characterized by aggressive strategic partnerships between major entertainment agencies and specialized software developers to streamline multi-city tour logistics. Notable recent developments include enhanced IP-protected geofencing firmware updates by leading operators to comply with tightening urban airspace safety regulations, alongside the commercial rollout of ultra-high-lumen LED payloads designed for daytime architectural and cultural performance applications.